For years, FICO was the credit score that really mattered when getting a mortgage.
That’s starting to change.
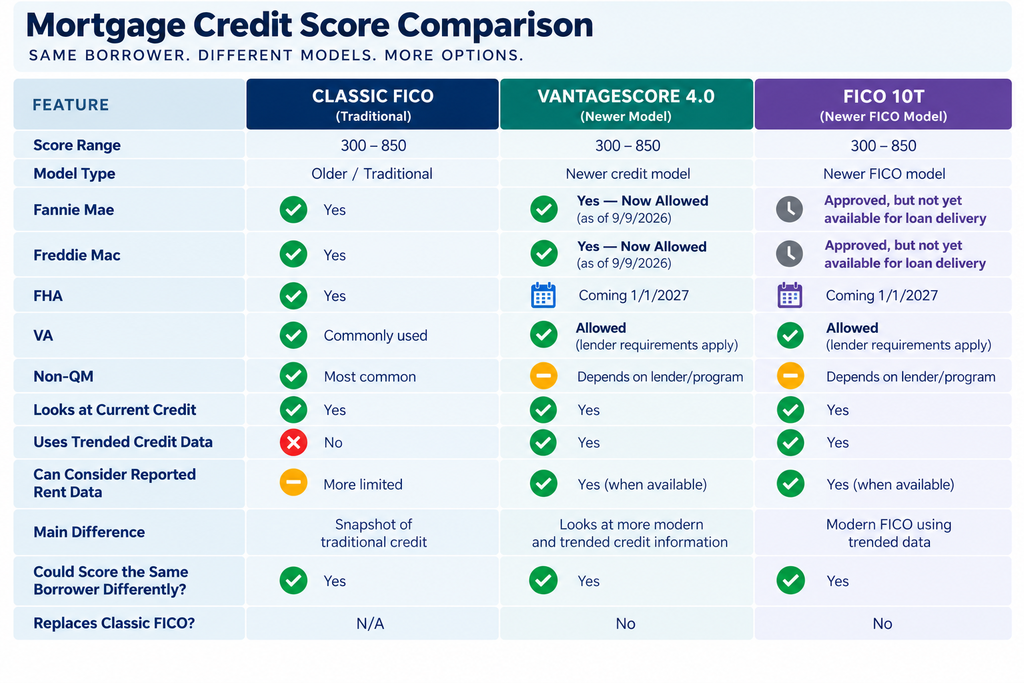
Newer credit scoring models like VantageScore 4.0 and FICO 10T are making their way into the mortgage world, which means the same borrower could potentially have a different score depending on the model being used.
That difference could matter when you’re trying to qualify for a loan.
Same Credit. Different Score.
Think about it this way. Your credit history hasn’t suddenly changed.
What’s changing is how that history is being evaluated.
Classic FICO gives lenders a more traditional look at your credit, while newer models can consider more of your credit behavior over time.
So two models can look at the same borrower and tell a slightly different story.
Why Does This Matter?
Because your credit score can affect much more than whether you’re approved.
It can influence your loan options, pricing and potentially how much your mortgage ultimately costs you.
That’s why seeing one score on a credit app and assuming that’s the number your mortgage lender will use doesn’t always tell you the full story.
Kenny’s Take
I think borrowers need to stop thinking of their credit score as one universal number.
As mortgage lending starts using different scoring models, the better question may be:
“Which credit score model are you using?”
If you’re close to qualifying or right on the edge of better pricing, that conversation could be more important than you think.
The Bottom Line
We’re entering a mortgage world where one credit score doesn’t necessarily tell the whole story anymore.
Classic FICO isn’t disappearing, but lenders now have access to newer ways of evaluating credit, and more changes are coming.
Same borrower. Same credit history.
Potentially a different score and a different mortgage conversation.
Every situation is different. Let’s find the right strategy for yours. Reach out and let’s talk.